 3 months vs 10 minutes
You chose the home slowly and the loan in ten minutes
You compared two flats for months. The loan went to whoever approved it fastest.
30 minutes · A one-to-one session · Vinod personally conducts every session
You’ve spent 3 months choosing your dream home, but you chose your home loan in just 10 minutes - based on which bank approved it fastest and offered the lowest interest rate. However, the loan you selected will ultimately cost you more.
Book My Home Loan Reality Check - Just ₹9 →"Zero interest" does not mean the bank stops charging interest. It means we use smart financial planning to help offset your interest cost through loan restructuring, an OD facility, SIPs and prepayments - without any additional cost.
If you are in the first list, thirty minutes from now you will know the real twenty-year cost of the biggest financial decision of your life, and whether that EMI is safe.
Book My Home Loan Reality Check - Just ₹9 →30 minutes · A one-to-one session · Vinod personally conducts every session
Forty seconds. You need nothing but your phone.
Open your calculator. Take your EMI. Multiply it by 12. Multiply that by your tenure in years. Now subtract the loan amount.
What is left is your interest, over the full term. Most people see it for the first time.
At 8.5 percent, a ₹50 lakh loan over 25 years costs about ₹70.8 lakh in interest. More than the loan.
Illustrative only. Your outcome depends on your lender.
3 months vs 10 minutes
You compared two flats for months. The loan went to whoever approved it fastest.
 Can, not should
That is how much you can borrow. Nobody asked how much you should.
 Four sellers
Builder, broker, bank, the relative with a number. Not one of them is on your side.
 Five extra years
 on a ₹50 lakh loan add about ₹16.7 lakh of interest. The EMI looks smaller, so the file moves faster.
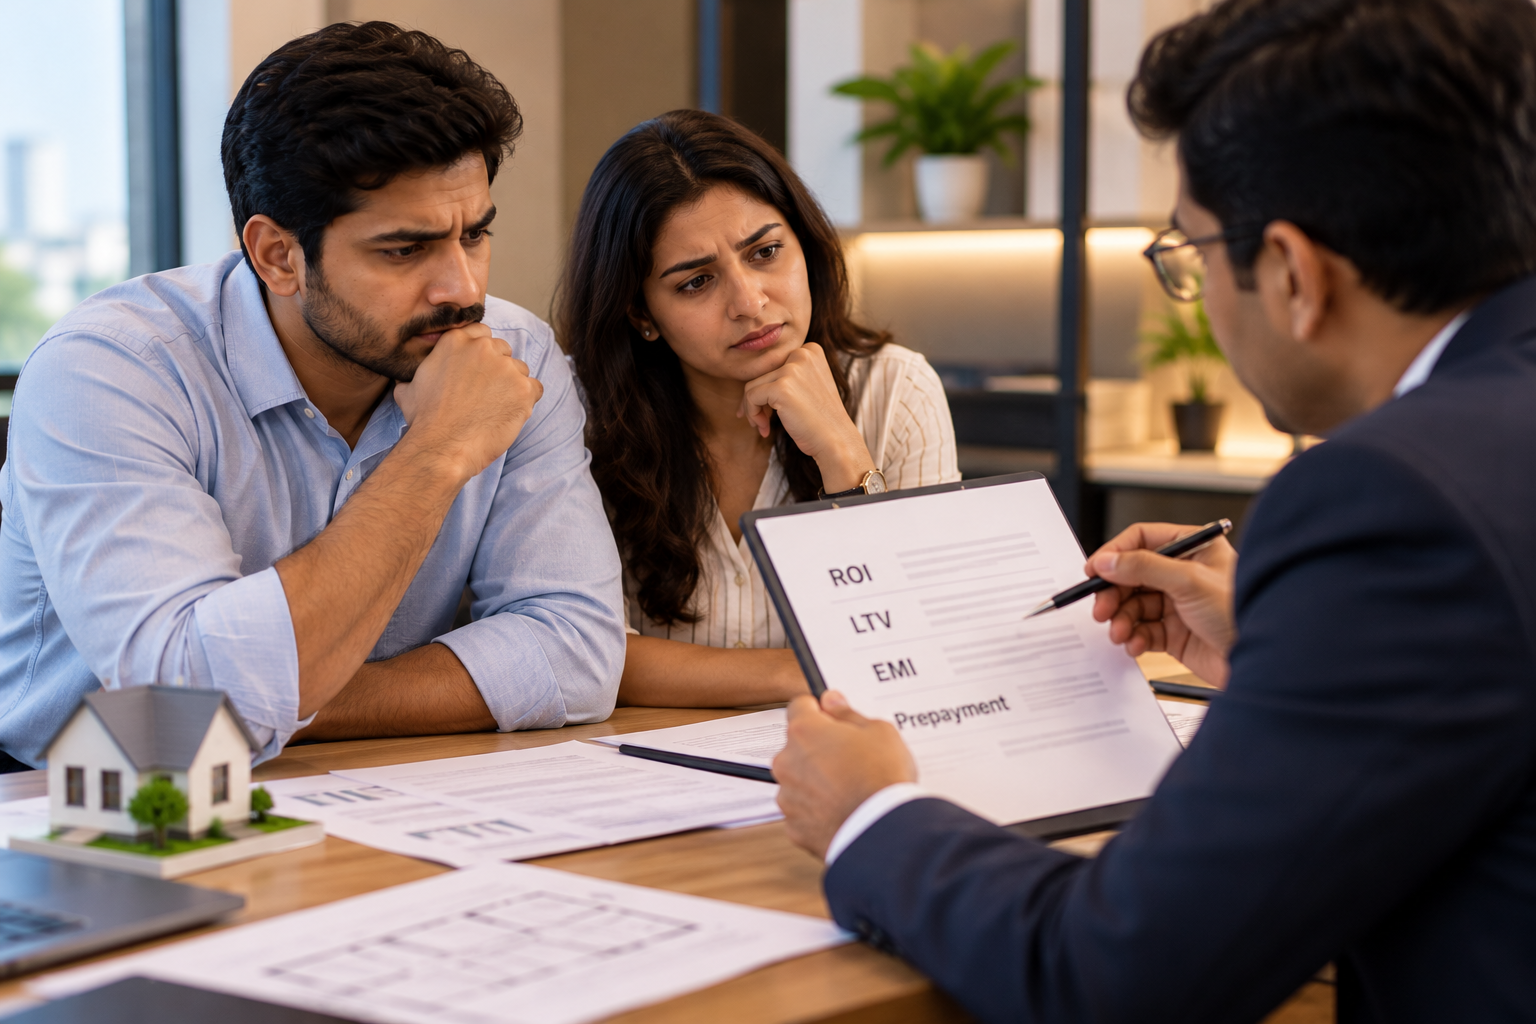 The question you skip
A word comes up that you do not know, so you nod. Then you sign for twenty years.
What is missing is not money or eligibility. It is one person paid by you, with no reason to care whether you buy.
This is not a claim and not a promise. It is arithmetic, and you just did it yourself on your own phone.
Book My Home Loan Reality Check - Just ₹9 →A one-to-one session. Vinod personally conducts every session.
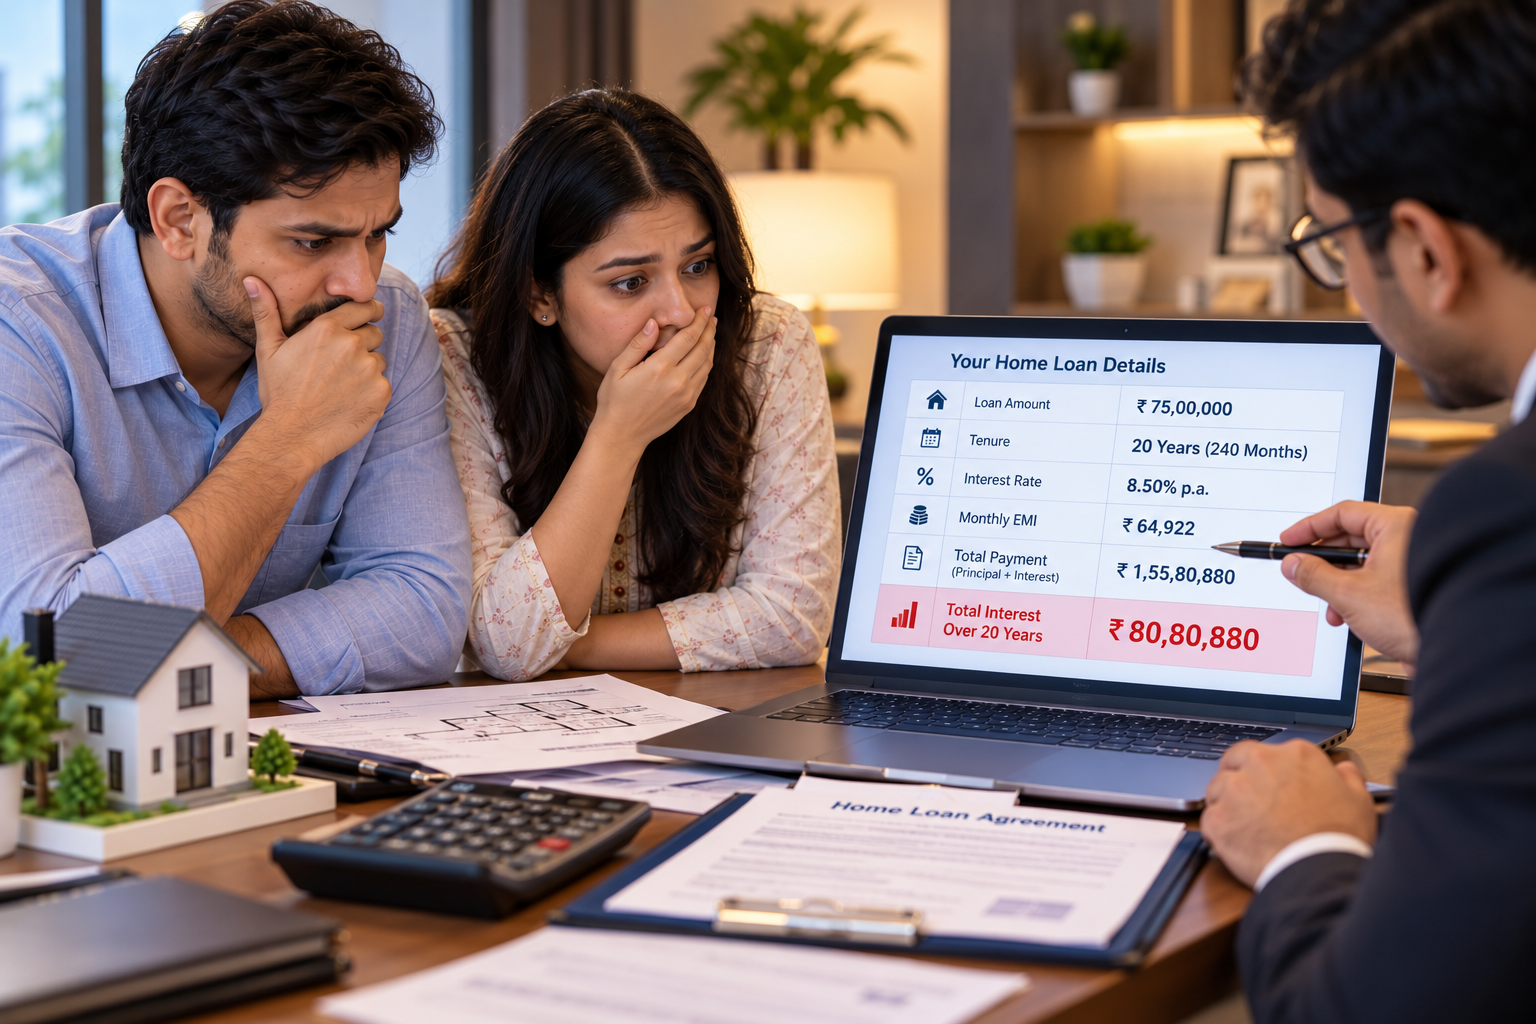
Your loan, your tenure, your rate, and the interest you will actually pay.
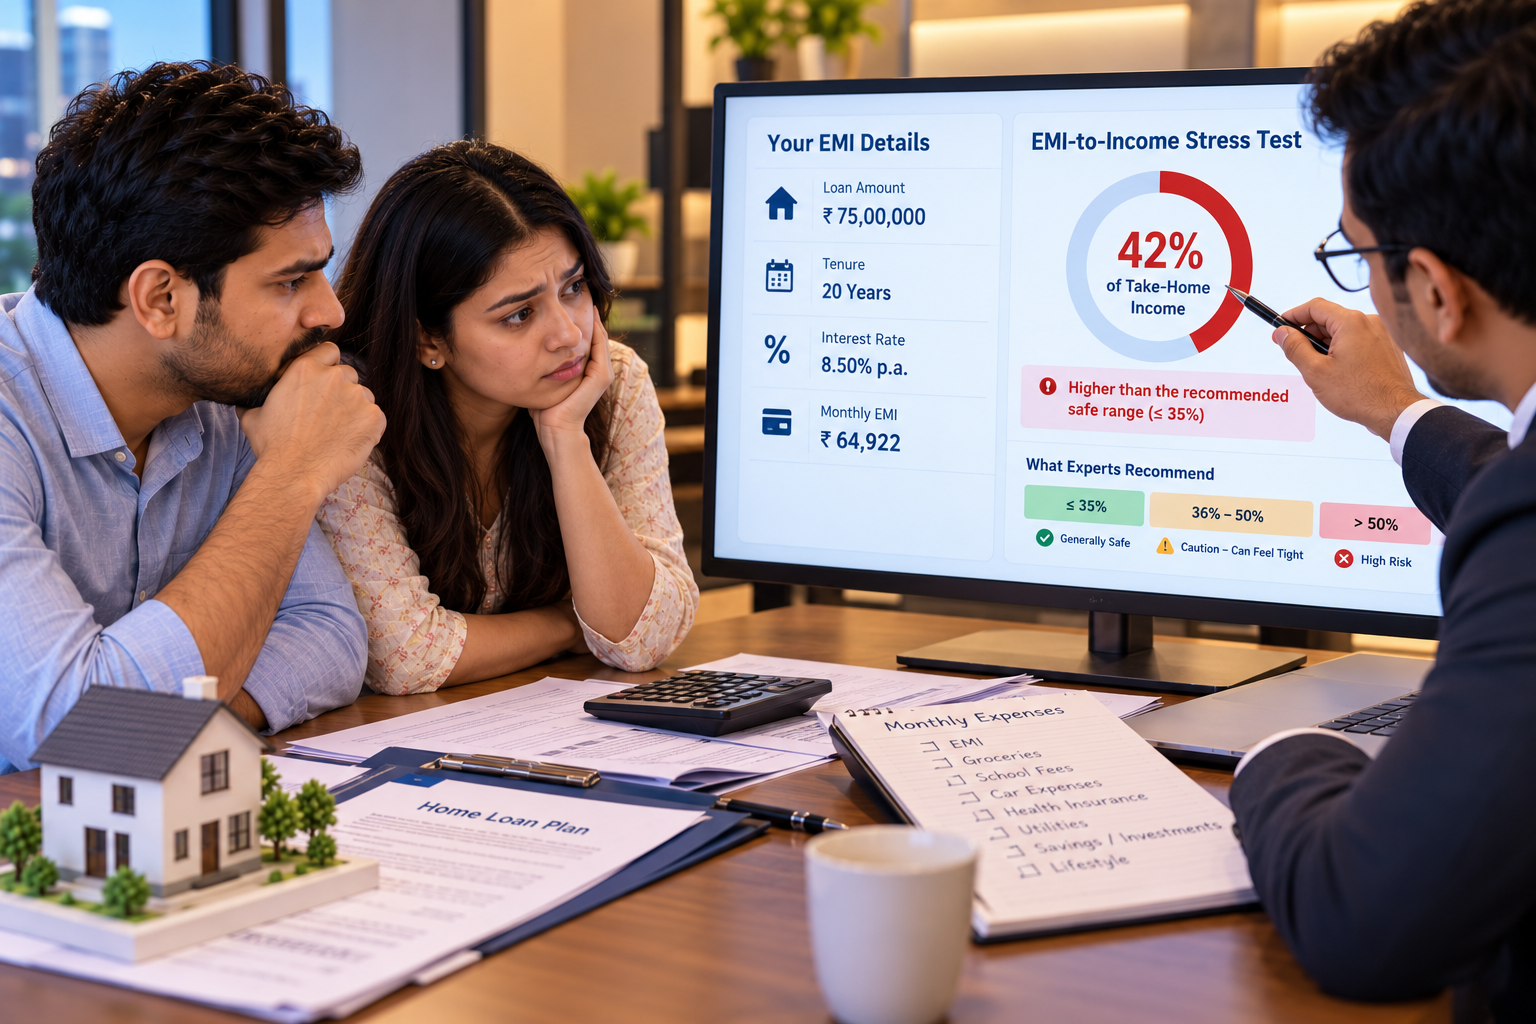
How much of your take-home it takes, and whether that is safe for twenty years.
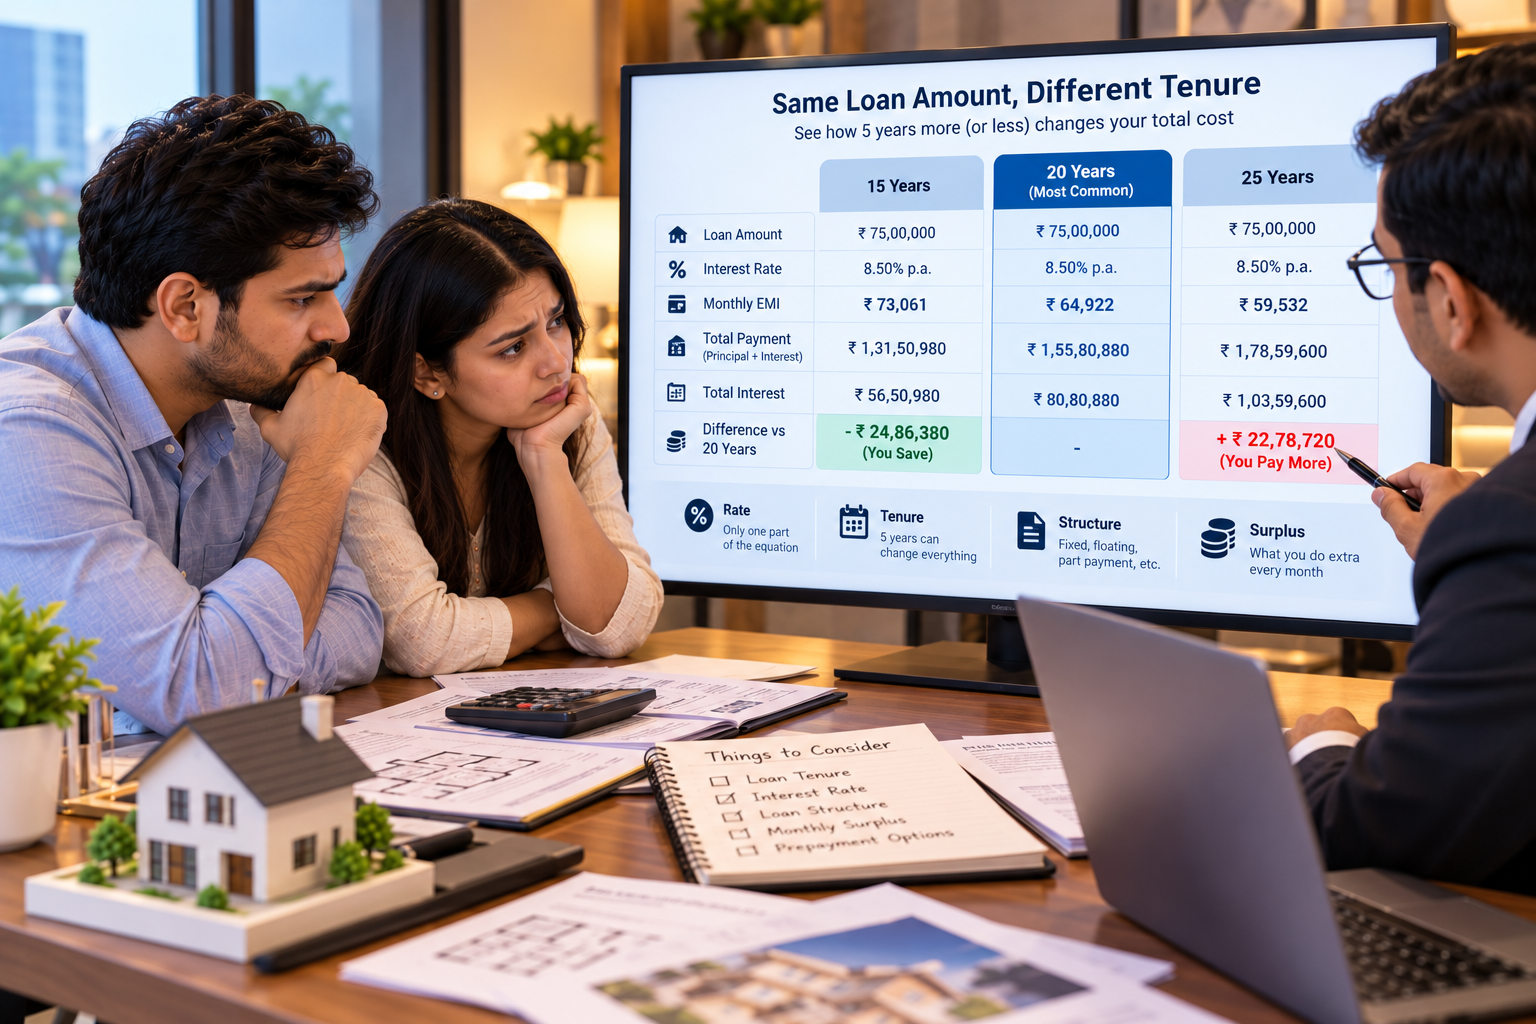
The rate is one of four things that decide the cost. Tenure, structure and your spare cash are the rest.
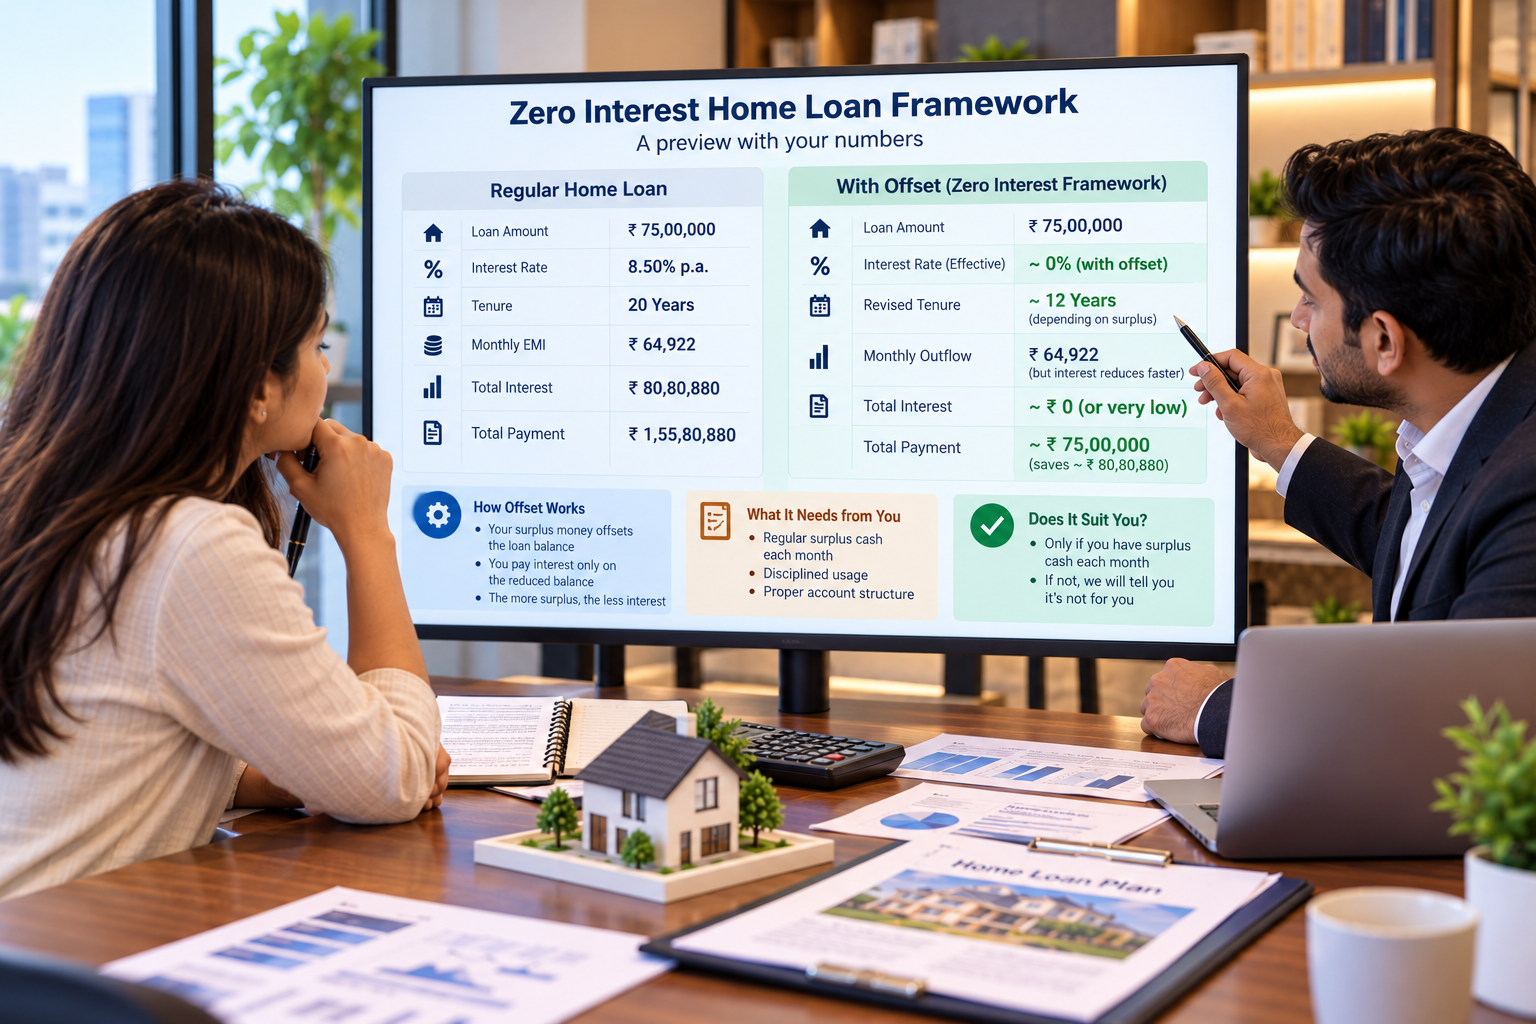
How the offset works and whether it suits you. With no spare cash each month, you will be told it is not for you.
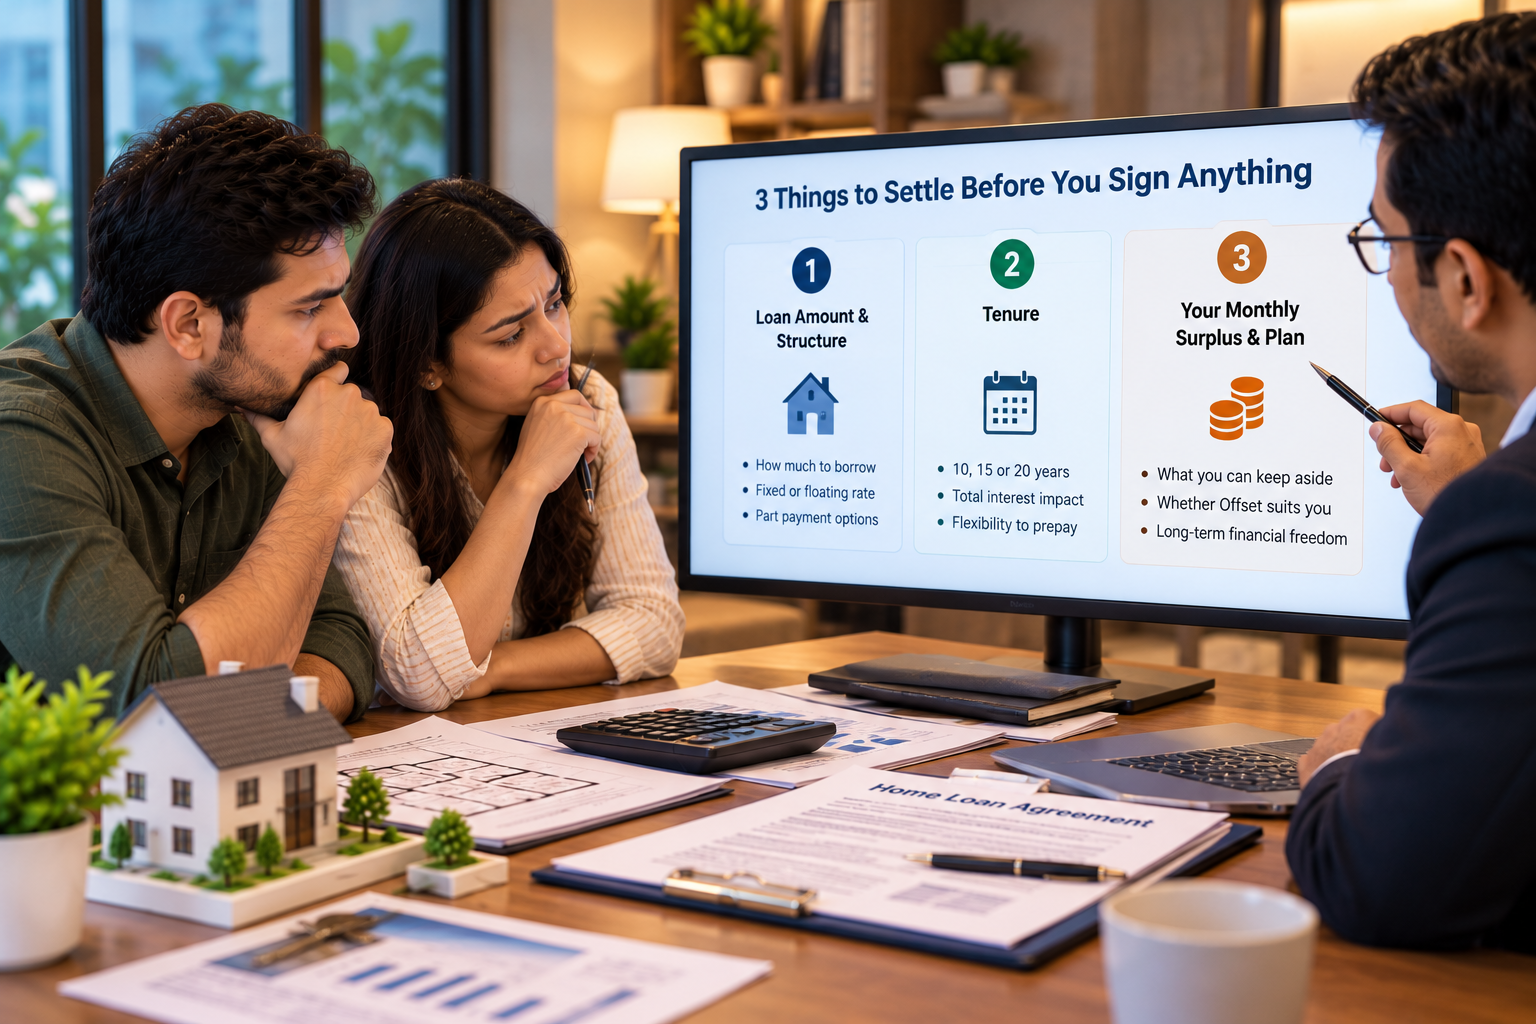
Not twenty. Three. The ones that cannot be fixed later.
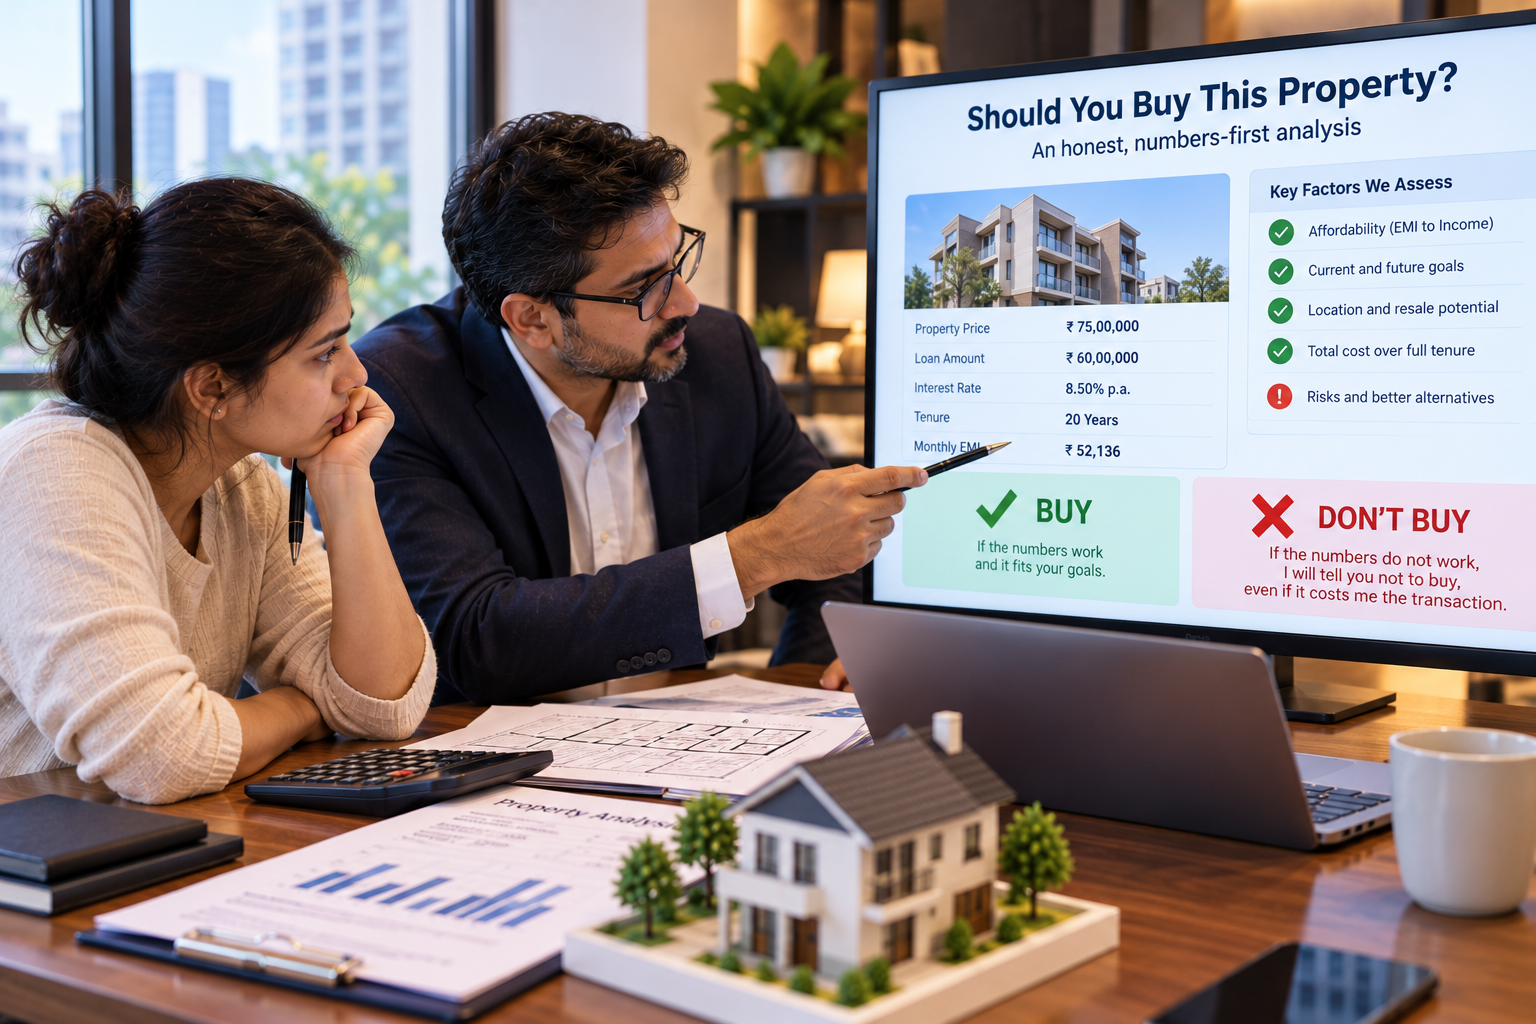
Including when the answer is no. Nothing is sold to you in the first twenty minutes.
Thirty minutes to see the real cost of the biggest decision of your life, before you promise it for twenty years.
Book My Home Loan Reality Check - Just ₹9 →Eighteen years, built only on people sending their friends and their colleagues.
18 years in real estate · Ex-banker
Vinod Shelar · FinProRealtors · Soaring RealFinTech Pvt Ltd
In property and home loan structuring
Of business, built on referrals, with no advertising until now
He has seen this from the other side of the desk
10 to 12 a week, no team, no call centre
In eighteen years he has watched hundreds of people buy a home, and one thing always bothered him. Three months choosing the flat. Ten minutes choosing the loan.
So he does it the other way round. The loan first, the structure first, the real number first, and the property after that.
"The broker gets paid when you buy. The bank gets paid when you borrow. I get paid when you decide - and sometimes that decision is no."
The rate is the only number anybody shows you, so that is the one everybody argues about. But it is one of four things that decide what a loan costs. The others are your tenure, your loan structure, and what your spare cash does each month in a savings account. Three of the four are in your hands, and nobody told you they exist.
The Zero Interest Home Loan Framework
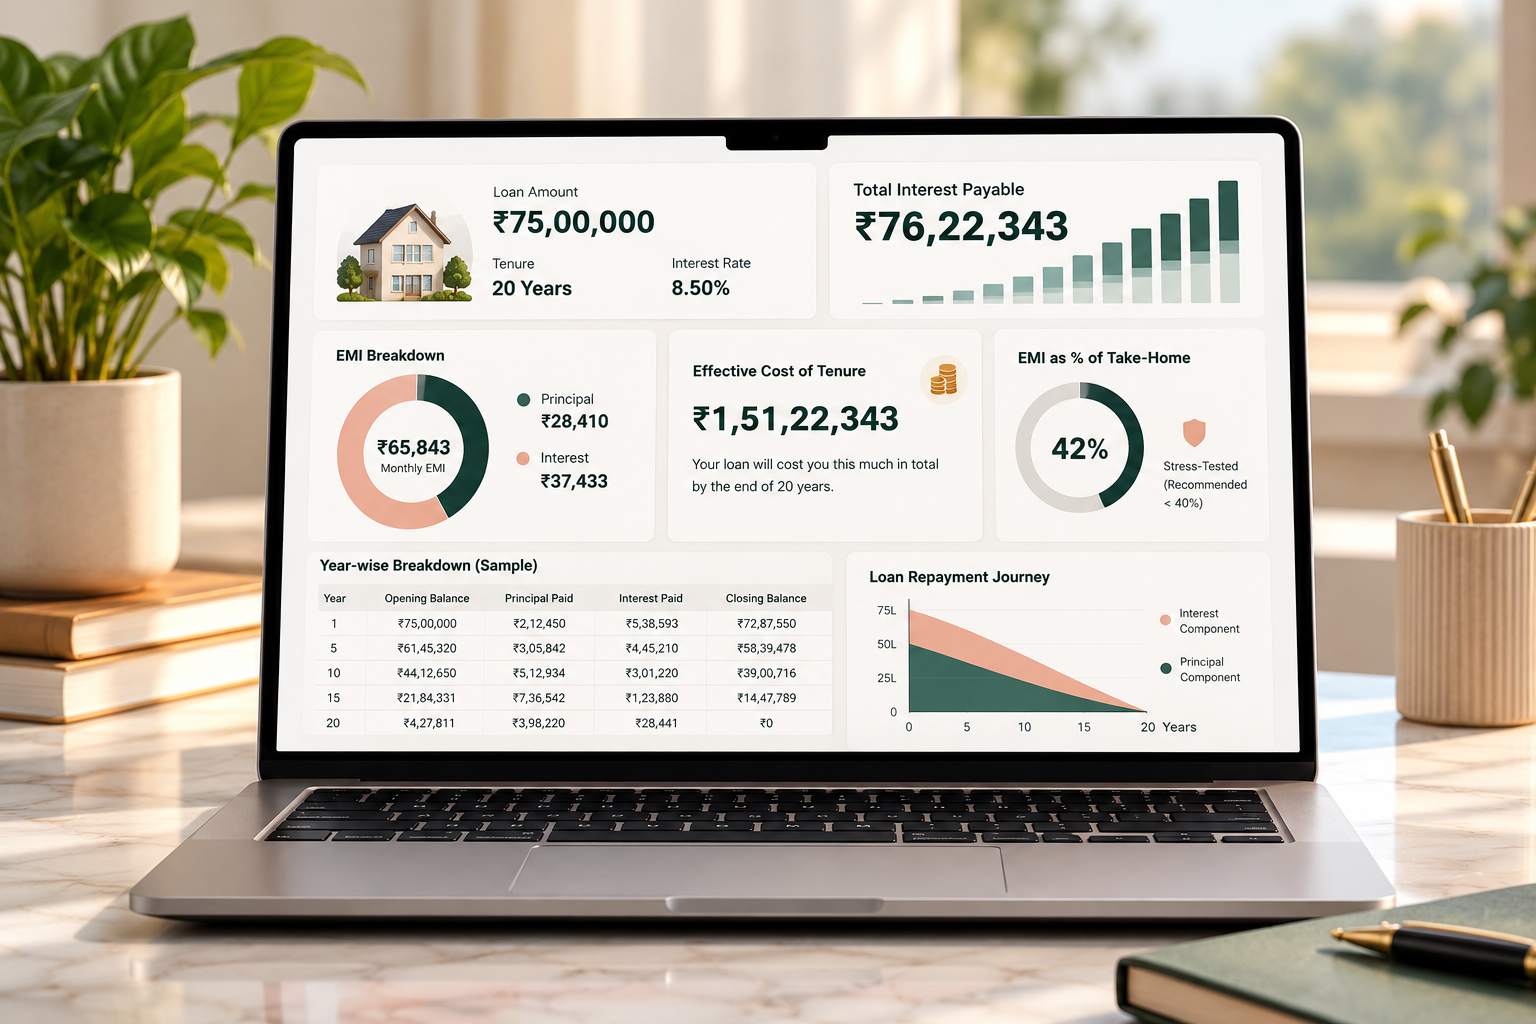
First the real number, then the right size of loan.
Result: The loan stops being whatever the first bank offered you.
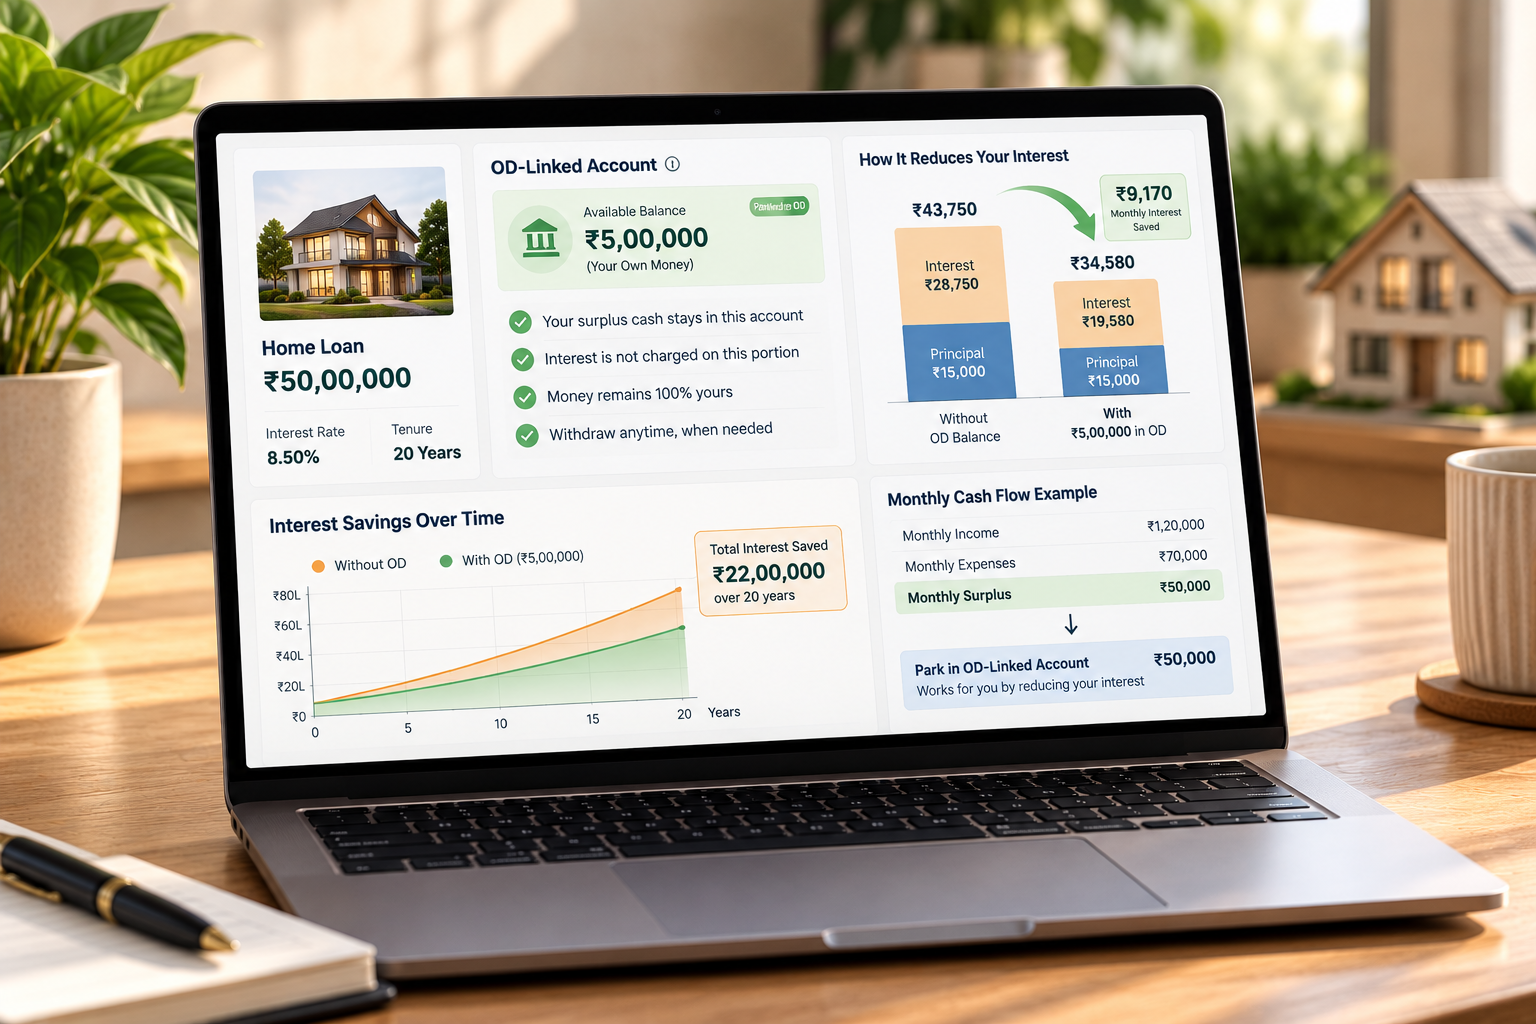
Your idle money stops sitting idle.
Result: The same money does two jobs instead of one.
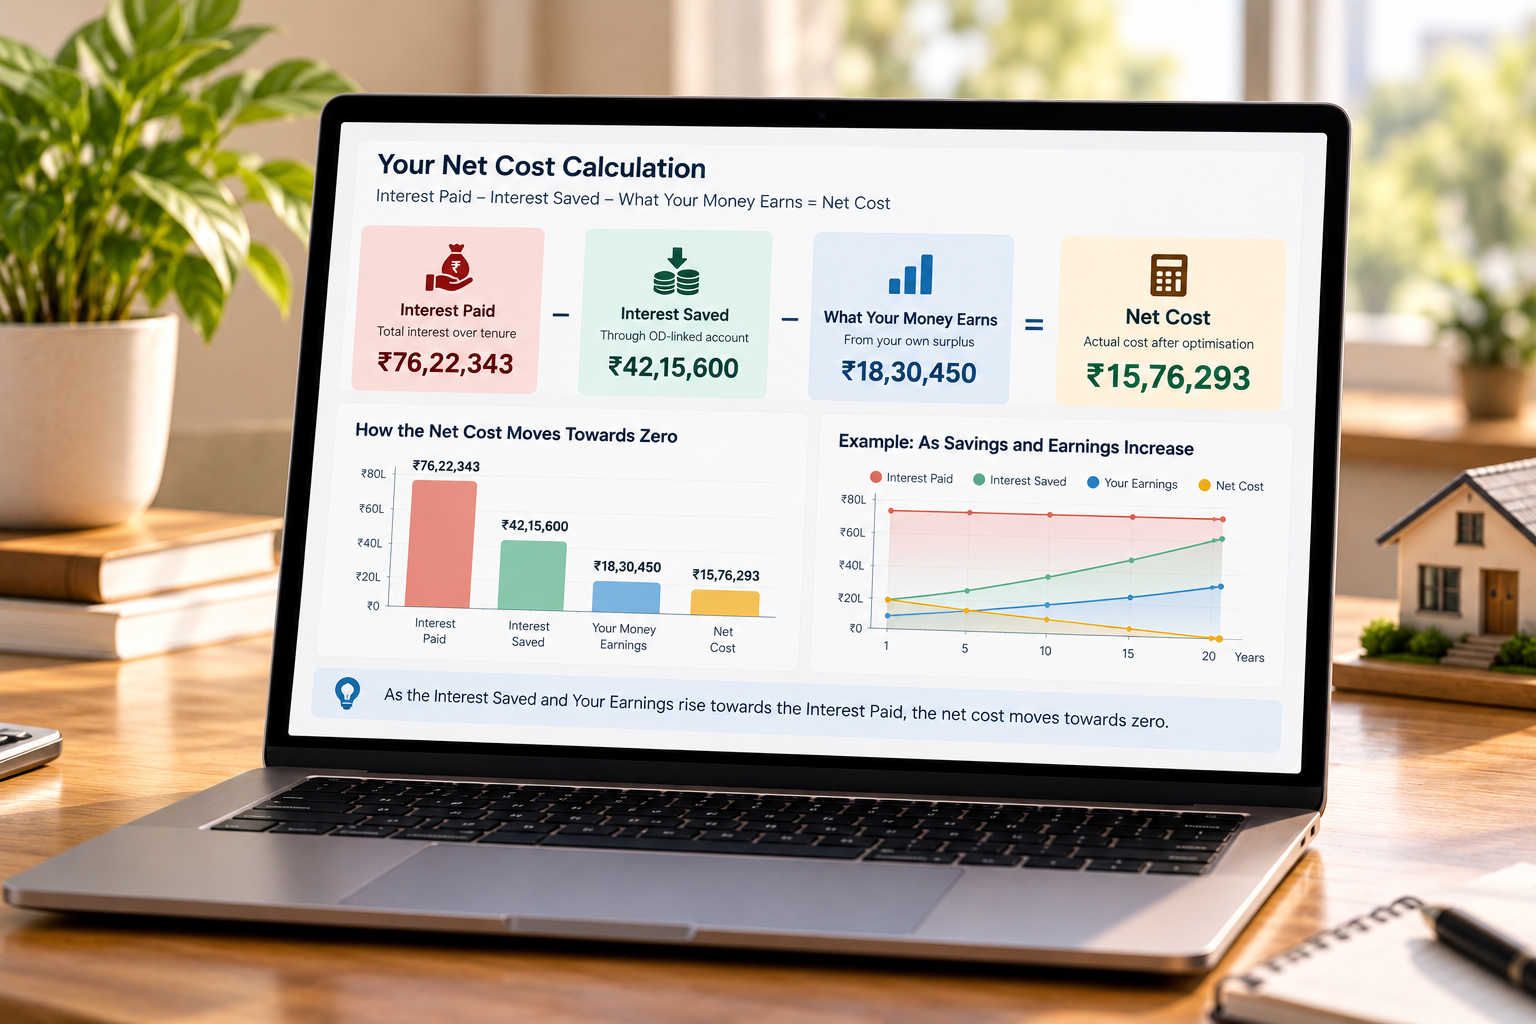
This is what the name actually means.
Result: You stop fixing one number out of four.
Interest paid, minus interest saved, minus money earned, is your real cost. Four levers, three of them in your hands, and the first one gets pulled in thirty minutes.
No team, no junior, no call centre. Ten to twelve is what one person can do properly alongside his existing clients.
That is also why it is ₹9 and not free. Free sessions get half the people turning up, and every empty slot is taken from somebody serious.
So take a slot, pay the ₹9, and answer four questions on WhatsApp - your budget, your loan amount, your tenure, and when you must decide.
Book My Home Loan Reality Check - Just ₹9 →
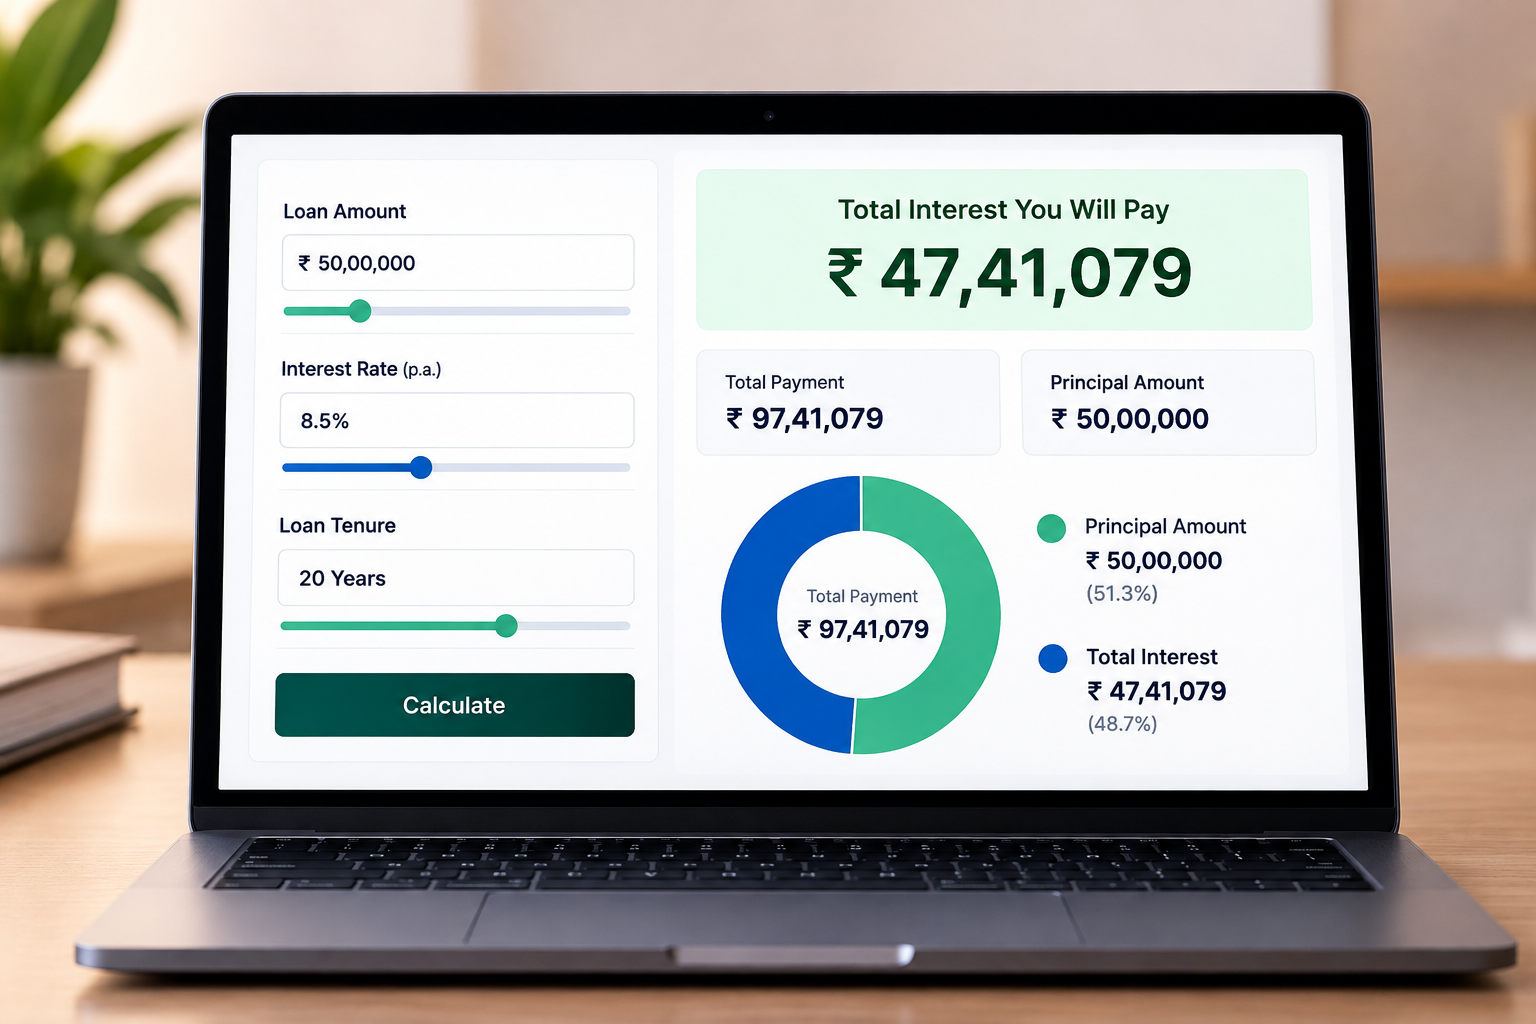
The total interest on your loan, worked out in front of you.
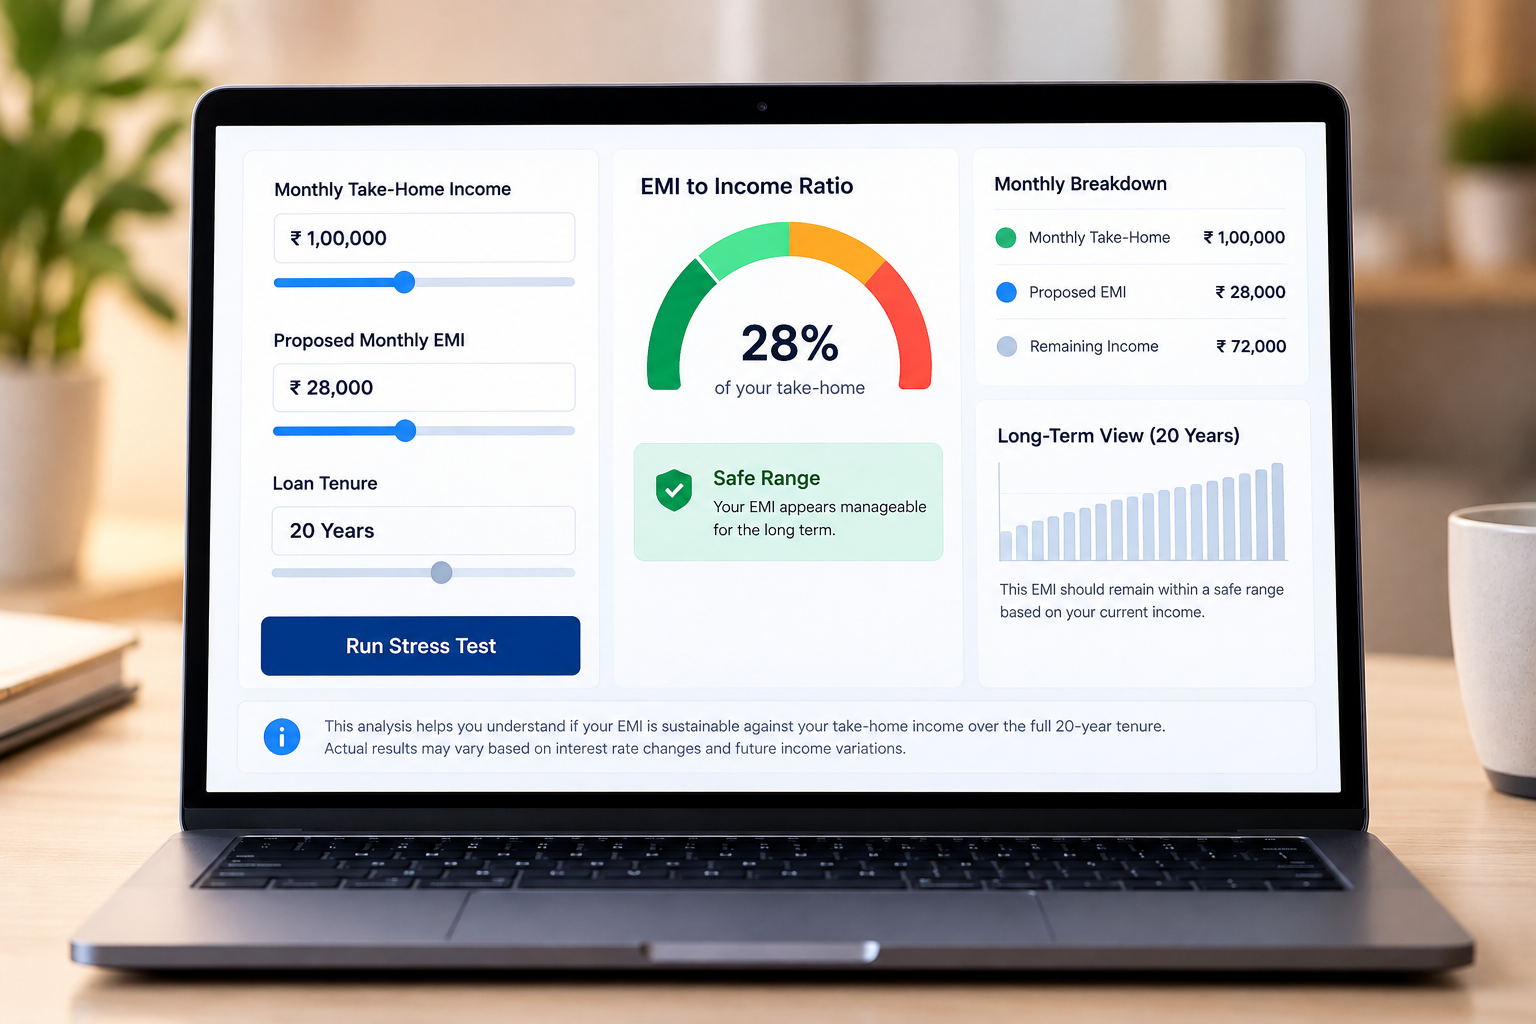
And a straight answer on whether it is safe.
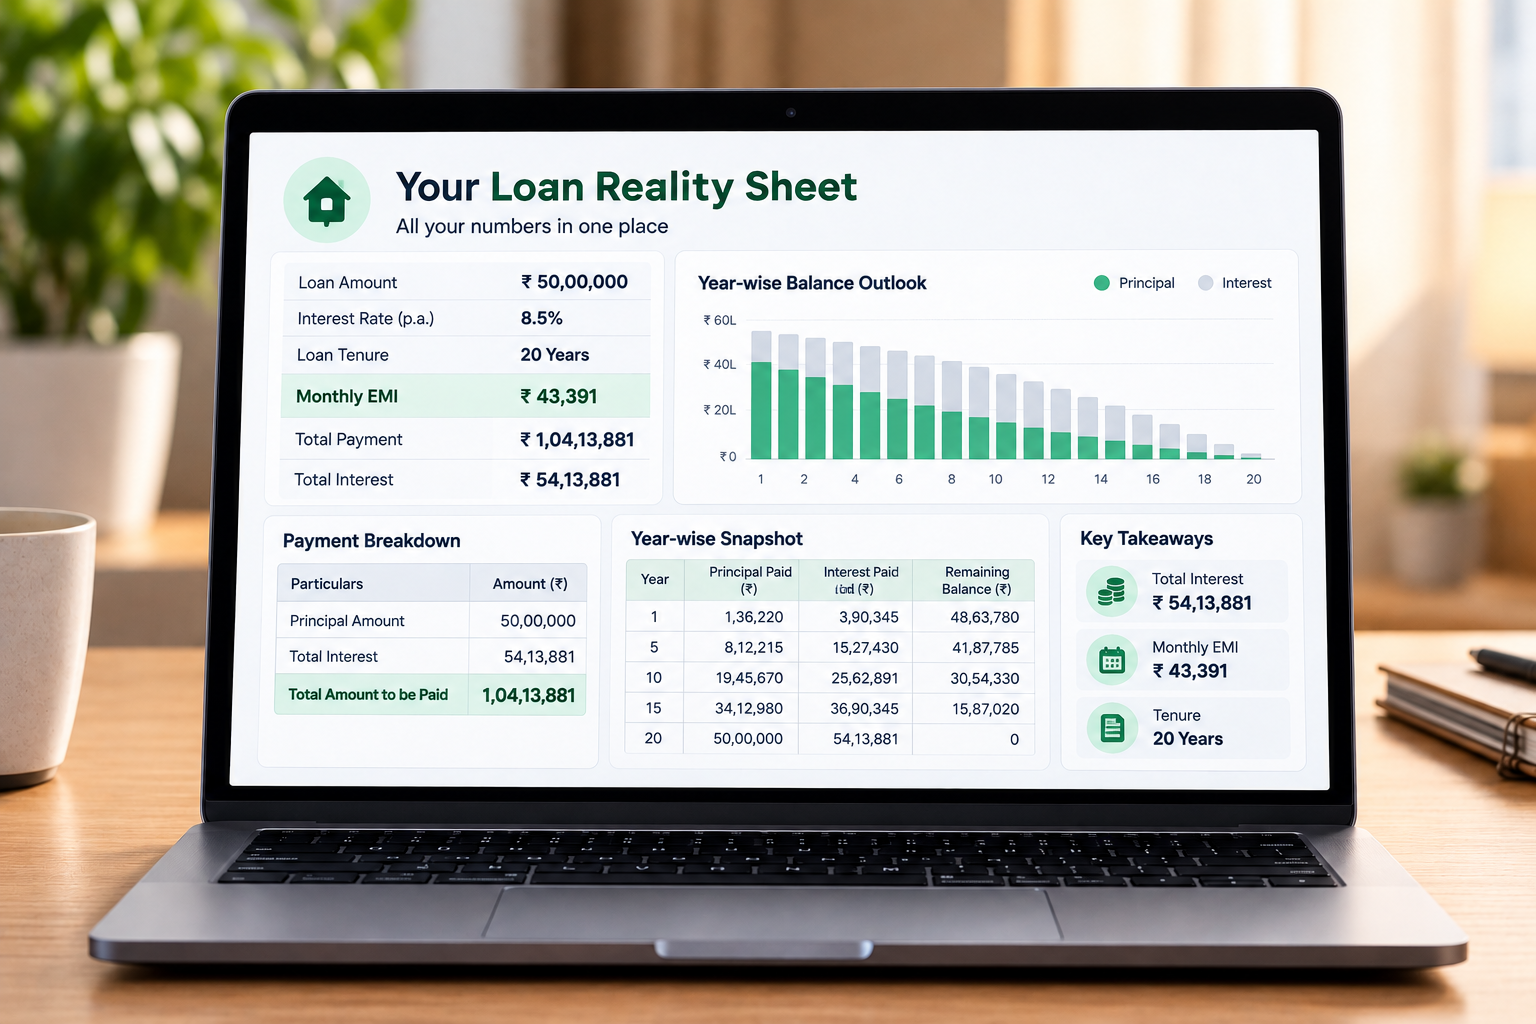
Your own numbers written out for your spouse and your CA.
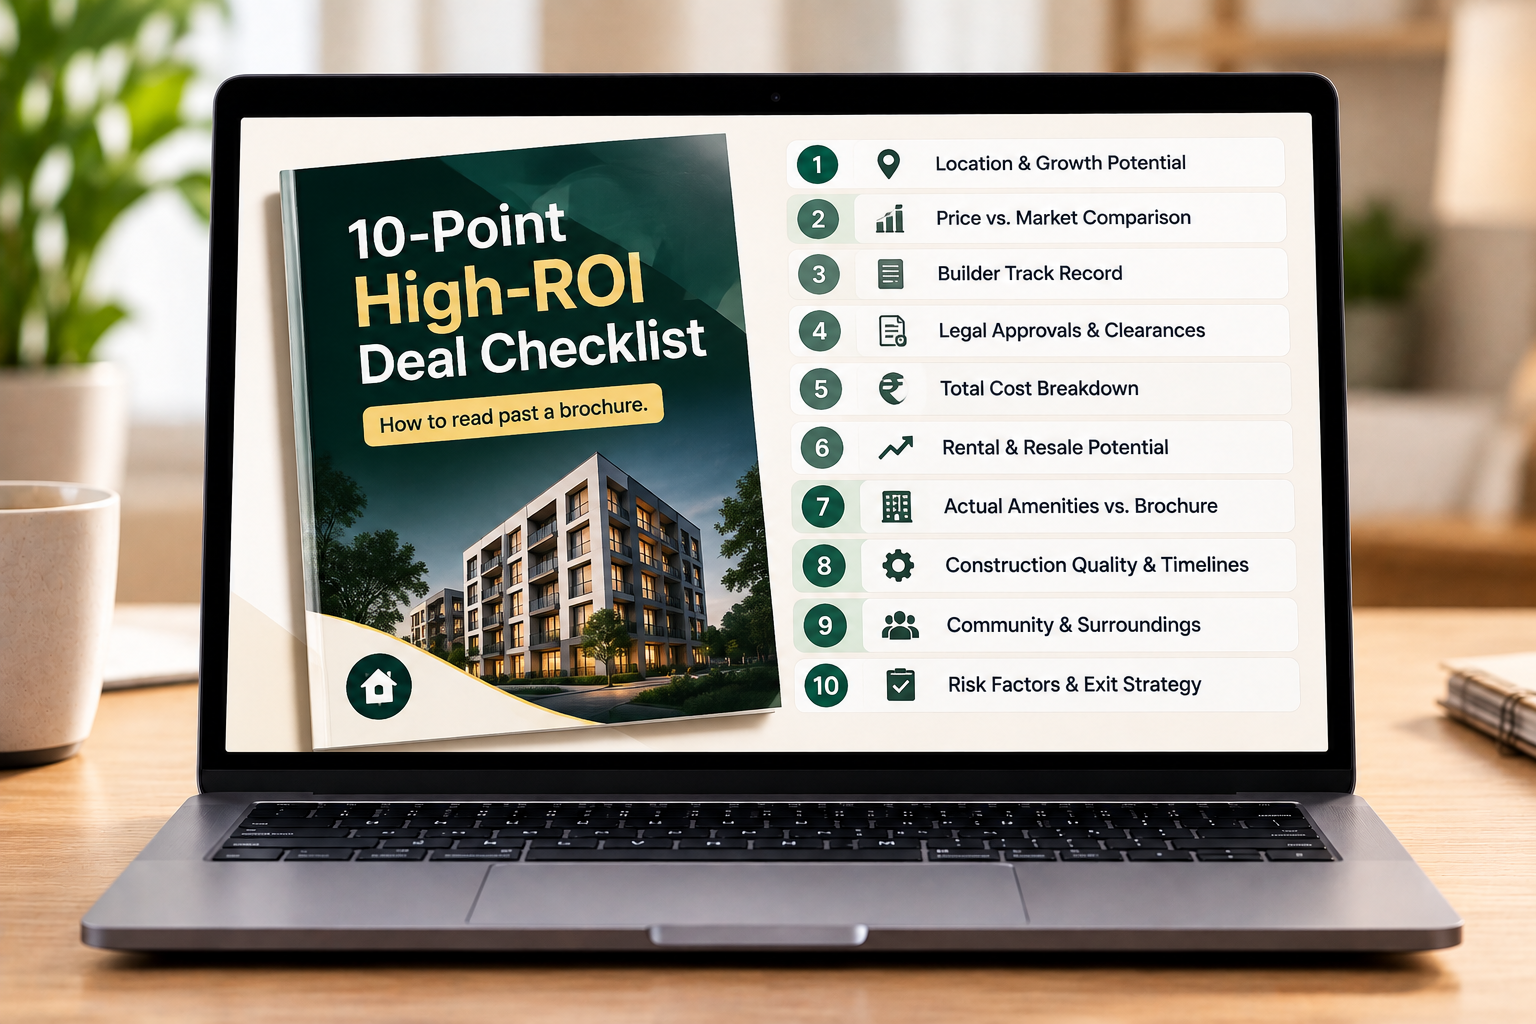
How to read past a brochure.
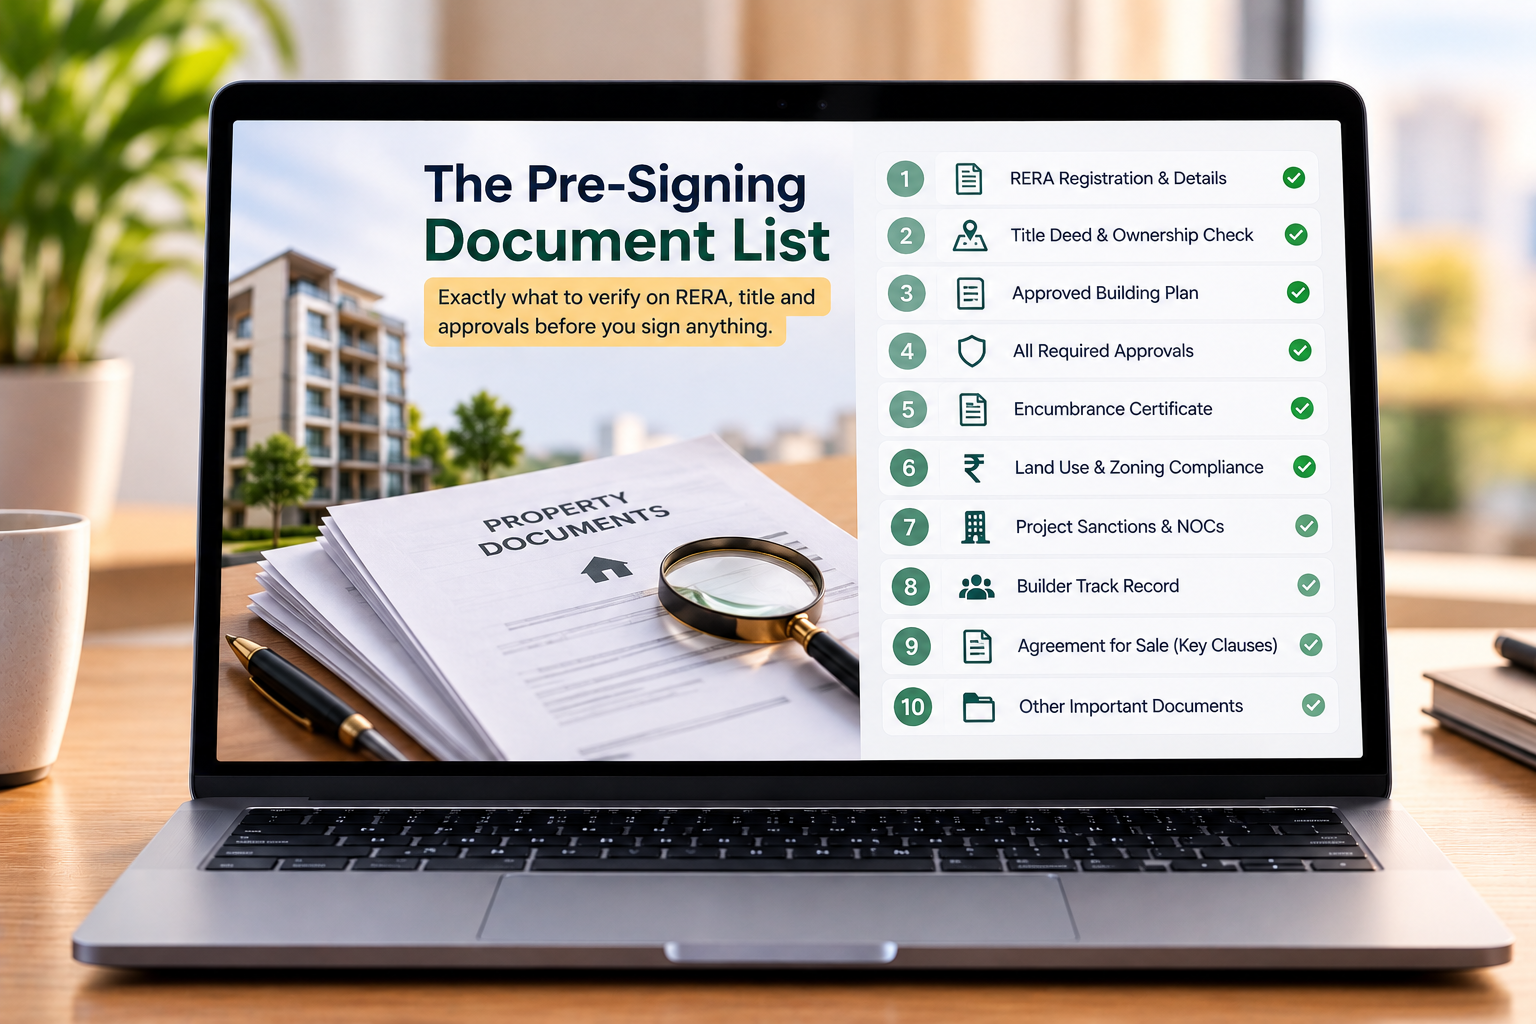
What to check on RERA, title and approvals before you sign.
Nothing to prepare. Four questions on WhatsApp, and the session starts with your numbers.
All three documents are yours to keep, whatever you decide next.
The 10-Point High-ROI Deal Checklist: ₹2,500
The Pre-Signing Document List: ₹2,500 · Your Loan Reality Sheet: Included
Documents alone: ₹5,000, plus the session itself
₹5,000 of documents, yours to keep. Your investment today: ₹9🔒 Secure payment · Slot and reminders on WhatsApp
You are about to promise a payment every month until you are nearly sixty, on a loan whose full cost you have never seen. This takes half an hour and nine rupees. The other version is signing on a Saturday and working the number out in the car.